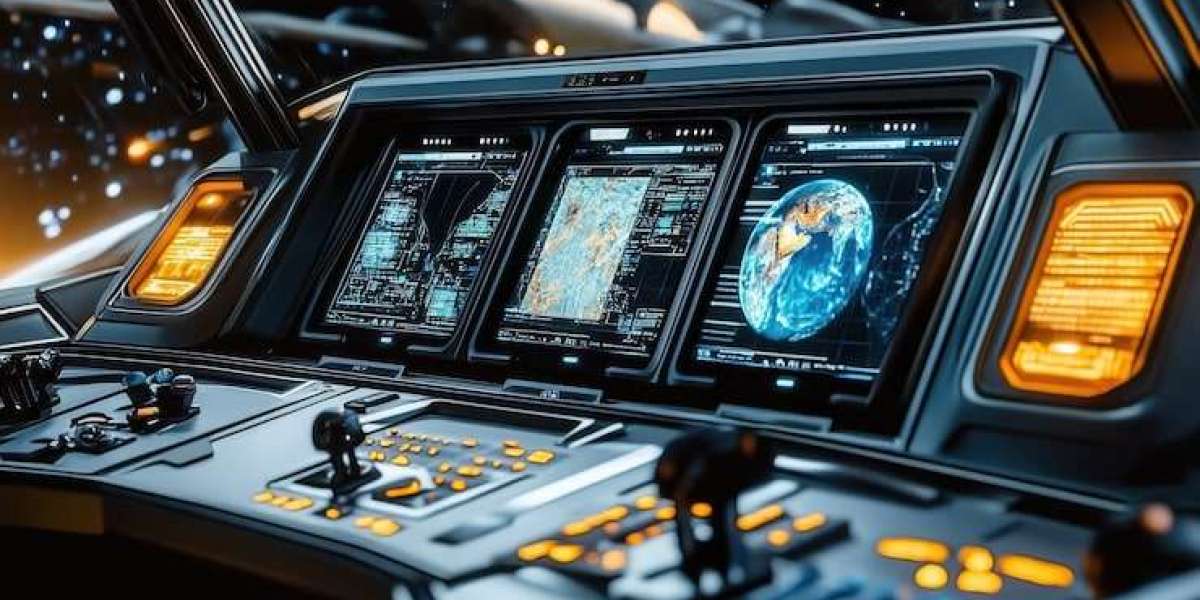

The global flight simulation systems industry is expanding as airlines, defense organizations, and aviation training providers seek more efficient ways to develop and maintain pilot competencies. Flight simulators recreate aircraft behavior and operational environments without requiring live flight for every training activity. Their applications span commercial aviation, military operations, unmanned aerial vehicles, recurrent training, emergency procedures, and mission rehearsal.
According to the Global Flight Simulation Systems Market research report by Markntel Advisor, the market was valued at around USD 6.00 billion in 2025 and is projected to reach USD 6.5 billion in 2026 and USD 9.2 billion by 2032. The market is expected to register a CAGR of approximately 5.96% during 2026–2032. North America holds around 32% of the market in 2026, while Full Flight Simulators and Synthetic Simulation account for approximately 45% and 70%, respectively.
Simulator-Based Training Gains Importance
The growing complexity of modern aircraft is increasing the need for realistic and repeatable training environments. Flight simulation allows pilots to practice normal operations, abnormal situations, emergency procedures, and aircraft-specific tasks without exposing crews or aircraft to the risks associated with live training.
The Federal Aviation Administration's flight simulation systems framework highlights the role of simulation in pilot training, aircraft development, and safety evaluation. Modern systems combine aerodynamics, flight dynamics, avionics, visual environments, motion systems, real-time computing, navigation, and other technologies to reproduce aircraft behavior and operational conditions.
Full Flight Simulators Maintain Leadership
Full Flight Simulators (FFS) represented approximately 45% of the global market by type in 2026, according to the report. Their strong position is associated with high levels of aircraft-system, motion, visual, and flight-dynamics fidelity. FFS platforms are widely used for type-rating, recurrent training, emergency procedures, and competency assessment.
The high fidelity of these systems allows training organizations to reproduce complex operational scenarios that can be difficult, expensive, or unsafe to conduct during live flight. Simulators can also replicate adverse weather, equipment failures, airport environments, and other conditions repeatedly, providing a controlled setting for structured training.
Synthetic Simulation Leads Training Methods
Synthetic Simulation accounted for approximately 70% of the market by training method in 2026. Synthetic environments allow training organizations to create repeatable scenarios involving aircraft systems, weather, airspace, terrain, and mission conditions. They can also support multiple types of training without requiring corresponding increases in live-flight hours.
Defense organizations use synthetic environments for mission rehearsal, tactical training, and operational preparation, while commercial operators use them for pilot proficiency and recurrent training. The ability to update digital scenarios also allows simulation systems to reflect changing aircraft configurations, operational procedures, and training requirements.
Regulatory Changes Encourage Technology Adoption
Regulatory developments are influencing the design and qualification of flight simulation training devices. In Europe, EASA introduced a new regulatory framework in 2026 that shifts FSTD qualification toward capabilities and fidelity levels and supports a task-to-tool approach for selecting appropriate devices for specific training objectives. The framework also accommodates newer technologies such as extended reality.
EASA states that its updated flight simulation training device framework is designed to support technological innovation while maintaining structured qualification requirements. The framework includes provisions for touchscreen interfaces, extended-reality technologies, and innovative training devices, indicating a broader regulatory acceptance of emerging simulation approaches.
Mixed Reality Expands Simulation Capabilities
Virtual reality and mixed reality are becoming increasingly relevant to flight simulation. These technologies can combine physical controls or cockpit components with digitally generated environments, allowing training organizations to create immersive scenarios without requiring the complete physical infrastructure of a traditional full-flight simulator.
Mixed-reality systems can also provide flexibility for specific training tasks. As regulators establish qualification pathways for newer technologies, training providers may have more options for matching simulation equipment with particular learning objectives. This can create opportunities for modular and specialized training devices alongside conventional high-fidelity simulators.
Commercial Aviation Drives Training Demand
Commercial aviation remains an important source of flight simulation demand as airlines expand fleets and manage increasing pilot requirements. New aircraft programs introduce updated avionics, flight-management systems, and cockpit interfaces, requiring pilots to receive type-specific training before operating them.
Fleet modernization can therefore create recurring demand for simulator capacity. Training providers and airlines may invest in additional full-flight simulators, flight training devices, and software upgrades to support new aircraft types and maintain training availability. Regional training centers can also expand capacity to serve growing pilot populations.
Defense Applications Support Market Expansion
Defense organizations represent another important user group for flight simulation systems. Military simulators can recreate aircraft missions, weapons-system interfaces, tactical environments, and complex operational scenarios. They allow pilots and crews to practice procedures repeatedly while reducing aircraft operating costs and exposure to unnecessary risks.
Synthetic training can also support joint exercises and mission rehearsal by connecting multiple simulated platforms and environments. This enables trainees to practice coordination and decision-making under controlled conditions while reducing the logistical requirements associated with large-scale live exercises.
Modular Devices Create Opportunities
The market is also developing beyond traditional full-motion simulators. Modular and lower-cost training devices can address specific training requirements while requiring less infrastructure than high-end full-flight systems. Flight schools, regional training centers, and specialized operators may use these devices for procedural, instrument, and task-specific training.
Such systems can be particularly relevant where training organizations need to increase capacity while controlling capital expenditure. Software-centric architectures can also allow training scenarios to be updated more efficiently as aircraft configurations and training requirements evolve.
Certification Remains a Key Challenge
Certification and compliance remain important considerations for simulator manufacturers and operators. FSTDs must meet detailed performance and fidelity requirements before they can be used for regulated training credits. Qualification processes can involve technical evaluation, documentation, testing, periodic surveillance, and continuing compliance.
The FAA's National Simulator Program establishes standards for FSTDs under 14 CFR Part 60 and conducts qualification activities. These requirements help maintain consistency between simulated and real aircraft behavior, but they can also increase development and operating costs, particularly for smaller manufacturers and training providers.
North America Leads the Market
North America accounted for approximately 32% of the global flight simulation systems market in 2026, according to the report. The region benefits from a large commercial aviation fleet, extensive military aviation activity, established pilot-training infrastructure, and the presence of major simulator manufacturers and training providers.
The United States is particularly important because of its large airline fleet and substantial defense aviation requirements. Regulatory oversight, simulator qualification infrastructure, and continued investment in pilot training further support regional demand for advanced simulation systems.
Outlook for the Flight Simulation Systems Industry
The global flight simulation systems market is expected to continue expanding through aviation fleet growth, pilot training requirements, regulatory developments, and increasing adoption of synthetic and immersive technologies. Full Flight Simulators remain the leading type, while Synthetic Simulation represents the dominant training method. North America maintains the largest regional share.
Future development will depend on advances in mixed reality, software-based simulation, artificial intelligence, modular training devices, and higher-fidelity digital environments. As aviation organizations seek safer, scalable, and more efficient training methods, flight simulation systems are likely to remain an important part of commercial, military, and specialized pilot-training infrastructure through 2032.